
In an economic environment defined by fluctuating public equity valuations, compressed traditional fixed-income yields, and persistent structural inflation, institutional allocators and accredited high-net-worth investors increasingly look beyond Wall Street. The traditional 60/40 portfolio—relying heavily on liquid public equities and sovereign or corporate bonds—often fails to deliver adequate capital preservation, inflation hedging, and steady cash distributions across market cycles.
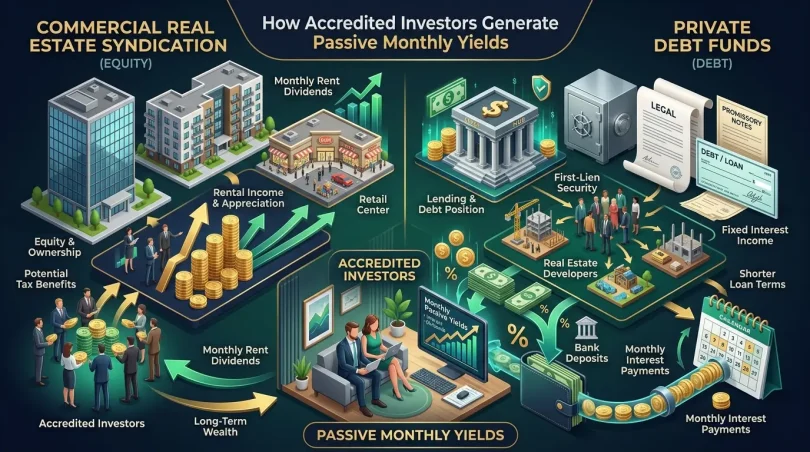
To secure reliable, non-correlated cash flow alongside tax-advantaged capital appreciation, sophisticated wealth managers allocate capital into private real estate markets. Within this asset class, two core institutional structures dominate: Commercial Real Estate (CRE) Syndications (private equity real estate) and Private Debt Funds (private credit and direct real estate lending).
While both structures offer direct exposure to commercial real estate assets, they operate on opposing sides of the capital stack. They feature contrasting risk profiles, return mechanics, distribution cadences, and tax treatments. Choosing between them—or constructing an optimal blended allocation—requires an understanding of debt and equity underwriting, waterfall distributions, legal due diligence under SEC Regulation D, and specialized tax codes.
1. The Institutional Shift: Public Markets vs. Private Real Estate Assets
Private commercial real estate investments differ substantially from publicly traded alternatives such as Real Estate Investment Trusts (REITs).
                      [ REAL ESTATE INVESTMENT LANDSCAPE ]
                                       │
        ┌──────────────────────────────┴──────────────────────────────┐
        ▼                                                             ▼
Publicly Traded REITs                                    Private Markets (Syndications & Credit)
* Traded on liquid public stock exchanges                • Illiquid private placement vehicles (Reg D)
* High beta correlation to broad stock market swings     • Zero public market correlation / mark-to-market noise
* Significant public-market volatility drag              • Tangible real estate collateral & underwriting control
* Distributed income taxed mostly as ordinary income     • Powerful tax sheltering (Cost Segregation / Depreciation)
* Liquid, but susceptible to panic-driven selloffs       • Multi-year investment horizon with structured liquidity
While public REITs offer daily liquidity, their share prices frequently move in tandem with broader equity market sentiment rather than underlying property fundamentals. During market corrections, public REIT shares can drop sharply even if physical property occupancy rates and net operating incomes remain robust.
Private real estate vehicles insulate capital from this mark-to-market volatility. By locking capital into multi-year private offerings, investors bypass emotional public trading, capture illiquidity premiums, and gain direct access to tangible assets managed by specialized operators.
Within these private markets, capital allocators face a fundamental strategic decision: take an equity ownership position via a real estate syndication, or act as a private lender through a debt fund.
2. Definitive Mechanics: Real Estate Syndication vs. Private Debt Funds
Understanding these vehicles requires analyzing their structural models, sponsor compensation, and capital flows.
                  [ REAL ESTATE SYNDICATION (EQUITY) ARCHITECTURE ]

                                  ┌─────────────────────────────┐
                                  │      General Partner (GP)   │
                                  │  (Sponsor: Sourcing, Ops)   │
                                  └──────────────┬──────────────┘
                                                 │
                                                 ▼
    ┌──────────────────────────┐  Equity Capital ┌─────────────────────────────┐
    │  Limited Partners (LPs)  │────────────────►│  Project Special Purpose    │
    │  (Accredited Investors)  │                 │        Vehicle (LLC)        │
    └──────────────────────────┘                 └──────────────┬──────────────┘
                                                                │
                                                   Acquires and │ Operates Physical Asset
                                                   Improves     ▼
                                                 ┌─────────────────────────────┐
                                                 │   Commercial Asset (e.g.,   │
                                                 │   250-Unit Multifamily)     │
                                                 └─────────────────────────────┘

-----------------------------------------------------------------------------------------

                  [ PRIVATE DEBT FUND (CREDIT) ARCHITECTURE ]

                                  ┌─────────────────────────────┐
                                  │        Fund Manager         │
                                  │ (Underwriting, Origination) │
                                  └──────────────┬──────────────┘
                                                 │
                                                 ▼
    ┌──────────────────────────┐  Debt Capital   ┌─────────────────────────────┐
    │     Fund Investors       │────────────────►│    Pooled Lending Fund      │
    │  (Accredited Investors)  │                 │    (Blind Pool LP / LLC)    │
    └──────────────────────────┘                 └──────────────┬──────────────┘
                                                                │
                                                     Originates │ Issues 1st-Lien Mortgages
                                                     Short-Term ▼
                                                 ┌─────────────────────────────┐
                                                 │ Diversified Portfolio of    │
                                                 │ 30–100+ Borrower Loans      │
                                                 └─────────────────────────────┘
Commercial Real Estate Syndication (Private Equity)
A real estate syndication is a partnership formed to pool capital for the acquisition, repositioning, operation, and eventual sale of a specific commercial property (such as a 300-unit multifamily community, an industrial logistics warehouse, or a suburban medical office complex).
- The General Partner (GP) / Sponsor: The professional operating team that identifies the asset, completes underwriting, secures acquisition debt, arranges equity financing, manages capital expenditures (CapEx), and oversees property management.
- The Limited Partners (LPs): The passive investors who provide the bulk of the equity capital (typically 80% to 95% of total required equity). LPs have no active management responsibilities or operational liability.
- Asset Structure: Syndications are typically single-asset vehicles structured as limited liability companies (LLCs) or limited partnerships (LPs). Investors know the exact property address, local tenant demographics, and physical building characteristics before committing capital.
- Return Profile: LPs participate directly in the property’s operational cash flows (quarterly or monthly distributions) and capture their share of equity appreciation upon a refinance or final sale.
Private Debt Funds (Private Credit)
A private debt fund is an open-ended (evergreen) or closed-ended pooled investment vehicle that originates or acquires real estate loans secured by commercial property. The fund functions as a specialized non-bank lender.
- The Fund Manager: The credit team responsible for setting underwriting guidelines, evaluating borrower creditworthiness, conducting property appraisals, managing loan-to-value (LTV) limits, and enforcing loan covenants.
- The Fund Investors: Passive allocators who deposit capital into a pooled fund. Rather than financing a single building, their capital is spread across dozens or hundreds of discrete real estate loans.
- Asset Structure: Typically structured as an open-ended “blind pool.” The manager originates short-term bridge loans, construction loans, or mezzanine financing for professional real estate operators.
- Return Profile: Returns are driven exclusively by contractually mandated interest payments and origination points paid by borrowers. Investors receive consistent monthly cash yields with no direct upside participation in property appreciation.
3. The Capital Stack Architecture: Risk-Return Hierarchy
Every commercial real estate transaction is governed by the Capital Stack. The capital stack defines the seniority of financial claims, the priority of cash disbursements, and the sequence of loss absorption if a project runs into distress.
                           [ THE REAL ESTATE CAPITAL STACK ]

      Position                     Risk / Return Profile              Payment Priority
┌──────────────────┐ ◄── Top       Highest Risk                       Fourth / Residual
│  Common Equity   │               Unlimited Upside Potential         (Paid last upon sale)
│  (Syndication)   │               Direct Tax Shielding Benefits
├──────────────────┤
│ Preferred Equity │               Moderate-High Risk                 Third Priority
│                  │               Fixed Return + Upside Hybrid       (Subordinate to debt)
├──────────────────┤
│  Mezzanine Debt  │               Moderate Risk                      Second Priority
│  (Private Credit)│               Higher Yield, Second Lien          (Junior to Senior)
├──────────────────┤
│   Senior Debt    │ ◄── Base      Lowest Risk                        FIRST PRIORITY
│  (Private Credit)│               Secured by 1st Lien Mortgage       (Absolute priority)
└──────────────────┘
1. Senior Debt (First-Lien Mortgage)
Senior debt sits at the absolute base of the capital stack, holding the lowest risk and the highest legal claim on the asset:
- Collateral: Secured by a recorded First Deed of Trust or First Mortgage on the underlying real estate.
- Payment Priority: Contractual interest and principal amortizations must be paid before any other party in the capital stack receives a single dollar.
- Downside Protection: If a borrower defaults, the senior lender holds the statutory right to foreclose on the property, wipe out all subordinate mezzanine debt and equity positions, take direct title to the physical asset, or force a judicial auction to recover principal.
- Typical Leverage: Represents 55% to 70% of the total property capitalization.
2. Mezzanine Debt (Second-Lien Financing)
Mezzanine debt fills the financing gap between senior debt and sponsor equity:
- Collateral: Unlike senior debt, mezzanine loans are typically secured not by the physical building itself, but by a pledge of equity ownership interests in the borrowing entity under the Uniform Commercial Code (UCC).
- Enforcement Mechanics: In a default scenario, a mezzanine lender can execute an expedited UCC foreclosure sale, allowing them to assume control of the equity entity that owns the property subject to the senior mortgage.
- Return Profile: Higher interest rates (typically 10% to 14%+) to compensate for subordinating payment priority to the senior mortgage holder.
3. Preferred Equity
Preferred equity occupies a hybrid position between debt and common equity:
- Payment Priority: Subordinate to all debt instruments, but senior to common equity partners for both ongoing cash distributions and capital returns upon exit.
- Return Mechanics: Often structured with a mandatory, cumulative preferred dividend (e.g., 9% to 12% annually), sometimes paired with a small profit participation (“kicker”) on exit.
- Remedies: Holds no mortgage lien, but operating agreements routinely grant preferred equity investors “change of control” rights to remove and replace the sponsor if preferred returns fall into arrears.
4. Common Equity (Syndication Equity)
Common equity sits at the top of the capital stack, bearing the highest risk while capturing uncapped upside:
- Payment Priority: Residual claim on cash flows. Common equity is paid only after property operating expenses, property taxes, insurance, senior debt service, and preferred equity dividends are fully satisfied.
- Downside Absorption: In a severe market downturn or operational failure, common equity absorbs the first dollar of loss. If an asset’s market value declines by 25% on a property financed with 70% debt, the common equity loses approximately 83% of its value.
- Upside Capture: Conversely, once operational performance surpasses underwriting targets, common equity captures 100% of residual appreciation, often generating outsized Internal Rates of Return (IRRs) and significant equity multiples.
4. Return Mechanics & Waterfall Distribution Models in Syndications
In an equity syndication, profits are split between the General Partner and the Limited Partners according to a contractual framework known as the Distribution Waterfall.
                       [ MULTI-TIER PROMOTED WATERFALL MODEL ]

   Gross Property Cash Flow / Net Sale Proceeds
                         │
                         ▼
   [ Tier 1: Return of Capital & Preferred Return ]
   • 100% of cash flows distributed to LPs until they achieve an 8.0% Preferred Return
     and recover their initial capital contribution.
                         │
                         ▼
   [ Tier 2: Hurdle One (e.g., 8.0% to 14.0% IRR) ]
   • Cash flows split 80% to Limited Partners / 20% to General Partner (Promote).
                         │
                         ▼
   [ Tier 3: Hurdle Two (e.g., Above 14.0% IRR) ]
   • Cash flows split 70% to Limited Partners / 30% to General Partner (Promote).
The Preferred Return (The “Pref”)
The Preferred Return is the contractual hurdle rate that passive investors must receive before the sponsor is entitled to share in residual operational profits or performance fees:
- Typical Range: Typically set between 6.0% and 8.5% annually.
- Cumulative vs. Non-Cumulative: In a Cumulative Preferred Return, if property cash flows are insufficient to pay the full pref in a given year (e.g., during heavy repositioning or unit renovations), the unpaid portion accrues and compounds into future years. The sponsor cannot take performance fees until all accrued preferred return deficits are cleared.
- Compounding: Cumulative prefs generally compound either monthly or annually on unpaid balances.
Sponsor Carried Interest and the “Promote”
The Promote is the performance fee paid to the General Partner as an incentive for generating returns above underwriting benchmarks.
- Once the preferred return hurdle is cleared, residual profits split along agreed percentages (e.g., an 80/20 split, where 80% flows to LPs and 20% to the GP).
- Tiered IRR Hurdles: Sophisticated institutional offerings employ escalating hurdles. For instance, the promote may sit at 20% until the project achieves a 14% IRR, escalating to a 30% or 40% promote for returns above a 18% IRR.
American vs. European Waterfall Models
The architectural design of a waterfall differs between single-asset syndications and multi-asset private equity real estate funds:
- American Waterfall (Deal-by-Deal): Common in single-asset syndications and early-stage funds. The GP calculates and collects their promote on each individual property liquidation. This structure benefits sponsors because they can earn performance fees on successful properties even if other assets in a broader portfolio underperform.
- European Waterfall (Whole-of-Fund): The institutional standard for multi-asset funds. The GP cannot collect any carried interest until investors have recovered 100% of their total invested capital across the entire fund, plus their cumulative preferred return across all properties. This model protects LPs from cross-deal performance drag.
Clawback Provisions
A Clawback Clause is an essential legal protection for LP investors. If a sponsor collects early promote distributions on strong initial performance, but subsequent asset struggles or market corrections pull the fund’s overall lifetime returns below the preferred return threshold, the clawback legally obligates the sponsor to return prior carried interest distributions to make the LPs whole.
5. Private Debt Economics: Spreads, Underwriting, and Collateral
Private debt funds operate under a different economic engine than equity syndications. Rather than looking for operational upside, private lenders generate predictable income by functioning as specialized bridge and construction lenders.
                  [ PRIVATE LENDING CASH-FLOW SPREAD MODEL ]

      Borrower Pays (Bridge Loan)                    Fund Economics & LP Distribution
┌───────────────────────────────────────┐         ┌───────────────────────────────────────┐
│ • Base Rate: SOFR Index (e.g., 5.0%)  │         │ • Gross Loan Yield:            11.50% │
│ • Spread:                    + 5.50%  │         │ • Servicing & Management Fee:  - 1.50%│
│ • Origination Points:        + 1.00%  │         │ • Loan Loss Reserve Drag:      - 0.50%│
│ ───────────────────────────────────── │         │ ───────────────────────────────────── │
│ Total Annualized Cost:        11.50%  │ ──────► │ Net Investor (LP) Yield:       9.50%  │
└───────────────────────────────────────┘         └───────────────────────────────────────┘
The Rise of Non-Bank Real Estate Lending
Following the Global Financial Crisis and subsequent regulatory frameworks (Basel III, Dodd-Frank, and heightened FDIC scrutiny), regional commercial banks pulled back from originating short-term, transitional real estate bridge loans.
This regulatory retreat created an opportunity for Private Debt Funds. Real estate operators turn to private credit funds when they require:
- Execution Speed: Private funds can underwrite, verify collateral, and close a bridge loan in 10 to 20 business days, compared to 60 to 90 days for traditional commercial banks.
- Flexible Structures: Private lenders offer interest-only periods, cross-collateralization, and structured renovation holdback facilities.
- Transitional Asset Financing: Traditional banks avoid properties undergoing heavy lease-up or deep renovations because they lack stable trailing twelve-month (T12) Debt Service Coverage Ratios. Private debt funds lend on “as-is” value while factoring in stabilized “as-completed” values.
Core Underwriting Metrics
Private credit fund managers protect capital by underwriting conservative collateral margins:
- Loan-to-Value (LTV): The ratio of the loan balance to the current fair market appraisal of the physical property:
$$\text{LTV} = \frac{\text{Loan Amount}}{\text{Current Appraised Value}}$$
Institutional private debt funds rarely exceed a 65% to 70% LTV on senior first-lien paper. This conservative cushion means property values must drop by more than 30% to 35% before the fund’s principal capital is exposed to loss.
- Loan-to-Cost (LTC): Measures the loan size against the total acquisition cost plus budgeted renovation capital:
$$\text{LTC} = \frac{\text{Loan Amount}}{\text{Purchase Price} + \text{CapEx Budget}}$$
LTC guidelines generally cap total exposure at 70% to 75%, requiring the real estate operator to fund the remaining 25% to 30% in cash equity.
- Debt Yield: Measures the property’s current cash flow against the loan exposure, independent of market interest rates:
$$\text{Debt Yield} = \frac{\text{Net Operating Income (NOI)}}{\text{Loan Amount}}$$
A debt yield of 10% or higher indicates the lender can recover their investment from property cash flows even if interest rates shift significantly.
- Debt Service Coverage Ratio (DSCR): Evaluates whether property revenues can cover loan payments:
$$\text{DSCR} = \frac{\text{Net Operating Income}}{\text{Annual Principal + Interest Payments}}$$
Security Covenants and Bad-Boy Guarantees
Private debt fund managers protect their investments using institutional legal agreements:
- First Deed of Trust / Mortgage: The primary legal lien recorded against the property title in local municipal registries.
- Assignment of Leases and Rents: If a borrower defaults, this covenant allows the lender to step in, collect rent directly from tenants, and use those cash flows to service the loan.
- Personal and “Bad-Boy” Non-Recourse Carve-Out Guarantees: While many commercial loans are non-recourse, sponsors must sign personal guarantees that convert the debt into full-recourse obligations if the borrower commits “bad acts” (such as fraud, material misrepresentation, voluntary bankruptcy filings, unauthorized secondary debt, or misappropriation of insurance proceeds).
6. Tax Engineering: Cost Segregation vs. Ordinary Income
Tax treatment is one of the most significant differences between real estate syndications and private debt funds. An equity investment offers exceptional tax sheltering, while a debt fund prioritizes predictable ordinary income.
                          [ TAX TREATMENT COMPARISON ]

       EQUITY SYNDICATION (IRC § 168 / § 469)           PRIVATE DEBT FUND (IRC § 61)
┌───────────────────────────────────────────────┐ ┌───────────────────────────────────────────┐
│ • Sheltered Cash Flow via Cost Segregation    │ │ • Interest Income = Ordinary Income Rates │
│ • Accelerated Bonus Depreciation Benefits     │ │ • High-bracket exposure (up to 37% Federal)│
│ • Passive Activity Losses (PALs) offset gains │ │ • Zero depreciation pass-through benefits │
│ • Long-term capital gains rates upon sale     │ │ • Best suited for tax-advantaged accounts │
│ • 1031 Exchange / DST deferral eligibility    │ │   (SDIRA, Solo 401(k), Dynasty Trust)     │
└───────────────────────────────────────────────┘ └───────────────────────────────────────────┘
Equity Syndications: The Power of Accelerated Depreciation
When an investor buys into an equity syndication, the tax code treats them as a direct property owner, allowing depreciation deductions to pass through onto their personal Schedule K-1.
1. Cost Segregation Studies
Normally, commercial real estate is depreciated on a straight-line schedule over 39 years (or 27.5 years for residential multifamily).
Under a Cost Segregation Study, licensed engineers inspect the property to reclassify building components into shorter depreciation schedules:
- 5-Year Property: Carpeting, specialized lighting, appliances, kitchen finishes.
- 15-Year Property: Land improvements, paving, fencing, exterior signage, landscaping drainage.
- 27.5 / 39-Year Property: The primary structural building envelope, foundational walls, framing.
2. Bonus Depreciation Mechanics (IRC § 168(k))
Under the Tax Cuts and Jobs Act (TCJA), properties qualified for immediate first-year Bonus Depreciation on assets with recovery periods of 20 years or less.
While 100% bonus depreciation began stepping down by 20% annually (80% in 2023, 60% in 2024, 40% in 2025, 20% in 2026) absent legislative extensions, cost segregation still generates substantial upfront paper losses:
[ Practical Impact of Cost Segregation & Bonus Depreciation ]
    Capital Invested by Limited Partner     : $100,000
    Year 1 Cash Distributions Received (8%) : $8,000 (Actual cash in bank)
    Pass-Through K-1 Paper Depreciation Loss: -$45,000 (Reported on Tax Form)
    ─────────────────────────────────────────────────────────────────────────
    Net Taxable Income for Year 1           : $0.00
    Unused Passive Loss Carried Forward     : -$37,000 to offset future gains
The investor receives an 8% cash yield completely shielded from current-year income taxes, while carrying forward excess paper losses to offset passive income in future tax years.
3. Passive Activity Loss Limitations (IRC § 469)
Under IRC § 469, losses generated from real estate syndications are classified as Passive Activity Losses (PALs).
- PALs can offset income from other passive investments (such as distributions from other syndications, limited partnerships, or rental properties).
- PALs cannot offset active W-2 wage earnings, active business income, or portfolio dividends—unless the investor or their spouse qualifies as a Real Estate Professional (REPS) under IRC § 469(c)(7), logging over 750 hours annually in real property trades or businesses.
4. Exit Deferrals: 1031 Exchanges and Delaware Statutory Trusts (DSTs)
Upon the eventual sale of a syndicated asset, capital gains and accumulated depreciation recapture taxes would normally come due.
Sponsors frequently execute an IRC § 1031 Like-Kind Exchange, rolling the gross sale proceeds directly into a larger commercial asset to defer taxes indefinitely. If an investor wishes to separate from the syndicate group at sale, sponsors can execute a “Drop-and-Swap” into a Delaware Statutory Trust (DST), preserving individual tax-deferral status.
Private Debt Funds: The Ordinary Income Environment
Private debt funds do not own real property; they own promissory notes and debt instruments.
- Tax Classification: Under IRC § 61(a)(4), interest distributions received from private debt funds are classified as interest income, which is taxed at ordinary federal income tax rates (up to 37%, plus applicable state taxes and the 3.8% Net Investment Income Tax).
- No Depreciation Pass-Through: Debt investors cannot claim depreciation, cost segregation deductions, or bonus write-offs to shield their returns.
- Optimal Placement: Because debt fund yields are taxed as ordinary income, accredited investors often hold their private credit allocations inside tax-advantaged retirement wrappers—such as a Self-Directed IRA (SDIRA) or a Solo 401(k). This allows high monthly yields to compound tax-free or tax-deferred without triggering annual tax obligations.
7. Regulatory Framework & SEC Compliance: Rule 506(b) vs. 506(c)
Both syndications and private debt funds rely on safe-harbor exemptions from registration under the Securities Act of 1933, regulated by the Securities and Exchange Commission (SEC) through Regulation D.
                         [ SEC REGULATION D LANDSCAPE ]

                   RULE 506(b)                            RULE 506(c)
┌───────────────────────────────────────────────┐ ┌───────────────────────────────────────────┐
│ • General solicitation strictly PROHIBITED    │ │ • General public solicitation PERMITTED   │
│ • Up to 35 non-accredited sophisticated peers │ │ • Strictly 100% ACCREDITED INVESTORS only │
│ • Relies on investor self-certification       │ │ • Mandatory third-party verification      │
│ • Requires pre-existing substantive relations │ │ • Widely marketed across digital platforms│
└───────────────────────────────────────────────┘ └───────────────────────────────────────────┘
The Accredited Investor Definition (Rule 501 of Regulation D)
To participate in most private placements, an individual must qualify as an Accredited Investor:
- Income Standard: An individual income exceeding $200,000 annually (or $300,000 combined with a legal spouse) in each of the two most recent calendar years, with a reasonable expectation of reaching the same income in the current year.
- Net Worth Standard: A personal net worth exceeding $1,000,000 (individually or combined with a spouse), excluding the primary residence.
- Professional Standard: Holding an active Series 7, Series 65, or Series 82 securities license in good standing.
- Entity Threshold: A business, trust, or family office with total assets exceeding $5,000,000 not formed for the specific purpose of acquiring the securities.
Rule 506(b): The Private Relationship Model
- Marketing Restrictions: The sponsor cannot engage in general advertising or public solicitation. They cannot discuss offering specifics on social media, open webinars, or public digital platforms.
- Investor Base: Can accept an unlimited number of accredited investors and up to 35 non-accredited, “sophisticated” investors.
- Accreditation Verification: Investors can self-certify their accredited status by checking a box on the subscription agreement.
- Operational Requirement: The sponsor must have an established, pre-existing substantive relationship with the investor before sharing private offering documents.
Rule 506(c): Public Offerings and Third-Party Verification
- Marketing Freedom: The sponsor can publicly advertise the offering across websites, podcasts, and digital channels.
- Investor Base: 100% of investors must be verified Accredited Investors. Non-accredited investors are completely barred from participating.
- Strict Verification Standards: The sponsor cannot rely on self-certification. Investors must provide verified proof through a third party (such as a formal letter from a licensed CPA, practicing attorney, registered broker-dealer, or specialized verification services like Parallel Markets), supported by tax returns, bank statements, or credit reports.
Primary Legal Documentation Package
Before investing capital into either vehicle, investors must review three essential documents:
- Private Placement Memorandum (PPM): The formal disclosure document outlining investment risks, conflicts of interest, fee schedules, property descriptions, and sponsor track records.
- Operating Agreement / Limited Partnership Agreement (LPA): The legally binding contract defining how the entity is run, voting thresholds, distribution waterfall mechanics, and GP removal provisions.
- Subscription Agreement: The transactional contract where the investor formalizes their capital commitment, confirms their accreditation status, and provides anti-money laundering (AML) identification.
8. Due Diligence Blueprint: How to Evaluate Deals and Managers
Investing in private markets requires independent due diligence. Without public quarterly filings and liquid secondary markets, investors must underwrite the sponsor’s operational competence, credit parameters, and market assumptions.
                          [ THREE-TIERED DUE DILIGENCE ENGINE ]

     Tier 1: Sponsor Underwriting             Tier 2: Asset / Market Underwriting       Tier 3: Structural Stress-Testing
┌───────────────────────────────────────┐  ┌───────────────────────────────────────┐  ┌───────────────────────────────────┐
│ • Track record across multiple cycles │  │ • Job growth & population metrics     │  │ • Reversion cap rate sensitivity  │
│ • Verification of full-cycle deals    │  │ • Submarket supply pipeline / permits │  │ • Breakeven occupancy thresholds  │
│ • Skin in the game (GP capital)       │  │ • In-place rent roll vs. pro-forma    │  │ • Debt maturity & refinance terms │
│ • Background checks & litigation scans│  │ • Basis relative to replacement cost  │  │ • Default rate history (Credit)   │
└───────────────────────────────────────┘  └───────────────────────────────────────┘  └───────────────────────────────────┘
Due Diligence: Real Estate Equity Syndications
When reviewing an equity syndication offering, evaluate these core assumptions:
- Exit Cap Rate Assumptions: The capitalization rate used to estimate the property’s sale price at the end of the investment horizon:
$$\text{Estimated Value at Exit} = \frac{\text{Projected Year-5 NOI}}{\text{Exit Cap Rate}}$$
Red Flag: Sponsors who assume their exit cap rate will be equal to or lower than their entry acquisition cap rate. In conservative underwriting, the exit cap rate should expand by at least 10 to 15 basis points per year of holding duration to account for building aging and capital market fluctuations.
- Debt Architecture: Examine the underlying financing terms:
- Is the debt Fixed Rate or Floating Rate?
- If the debt is floating, did the sponsor buy an extended Interest Rate Cap? At what strike price?
- When does the debt mature, and what are the extension options? (Many syndications ran into trouble between 2022 and 2024 because they used unhedged, short-term floating-rate debt).
- Sponsor Track Record and Full-Cycle Experience: Has the sponsor navigated an entire economic cycle (including acquisition, repositioning, and profitable sale) through a recession or rising-rate environment? Review their track record to see how they handled past tenant distress, supply chain bottlenecks, and contractor delays.
- Skin in the Game: How much personal cash equity are the GP principals investing into the common equity alongside LPs? Look for sponsors who invest 5% to 10%+ of the total required equity, ensuring financial alignment if performance lags.
Due Diligence: Private Debt Funds
When evaluating a private credit fund, focus on portfolio construction and risk controls:
- Historical Default and Loss Rates: Review the fund’s historical loan performance:
- What percentage of originated loans went into default (30, 60, 90+ days past due)?
- What were the fund’s net realized capital losses after foreclosing and selling the underlying properties? A strong manager may have defaults, but conservative LTVs should keep realized principal losses near zero.
- Average Weighted LTV: Confirm the fund’s average loan-to-value stays below 65% to 70%. Lower LTVs provide a wide margin of safety if property values decline.
- Origination Infrastructure: Does the fund originate its own loans using an in-house team, or do they buy loans from third-party brokers? Direct origination allows for tighter underwriting control, deeper borrower background checks, and higher origination fee retention.
- Concentration Limits: Confirm the fund’s operating documents enforce strict diversification limits: no single loan should represent more than 5% to 10% of total fund capital, and capital should be spread across multiple asset classes and geographic regions.
9. Comprehensive Comparison: Real Estate Syndications vs. Private Debt Funds
| Investment Feature | Real Estate Syndication (Equity) | Private Debt Fund (Credit) |
|---|---|---|
| Capital Stack Position | Top of the Stack (Common Equity) | Base of the Stack (Senior 1st-Lien Debt) |
| Primary Investment Objective | Long-term capital growth, upside appreciation, tax write-offs | Consistent, predictable monthly cash income and capital preservation |
| Typical Target Yield | 6.0% – 8.0% annual cash flow (14% – 18%+ Target IRR) | 8.5% – 11.5%+ Net Annualized Cash Yield |
| Upside Participation | Uncapped; participation in all residual equity gains | Zero; capped strictly at contractual note interest |
| Distribution Frequency | Quarterly or Monthly (dependent on property cash flow) | Monthly (consistent, contractual borrower interest) |
| Liquidity & Lockup Terms | Highly illiquid; 3 to 7+ year holding period until asset sale | Semi-liquid; often 1-year lockup with quarterly redemption terms |
| Tax Reporting | Schedule K-1 (Pass-through depreciation / PALs) | Form 1099-INT or Schedule K-1 (Ordinary interest income) |
| Tax Advantages | Exceptional; Cost segregation, bonus depreciation, 1031 exchanges | Minimal; interest income taxed at ordinary income tax rates |
| Collateral Security | Ownership interest in the property entity | First Deed of Trust / Mortgage directly on real estate |
| Downside Risk Profile | Absorbs first loss; vulnerable to market valuation declines | Insulated by 30%–35% equity cushion below the loan |
| Account Compatibility | Taxable personal accounts, Family Trusts, High-tax entities | Tax-Advantaged Accounts (SDIRA, Solo 401(k)), Family Offices |
10. Portfolio Construction: The Core-Satellite Hybrid Allocation
Rather than choosing between real estate syndications and private debt funds, high-net-worth investors and family offices combine both to balance cash yield and tax-sheltered appreciation.
                    [ BALANCED PRIVATE REAL ESTATE ALLOCATION ]

                                 TOTAL PORTFOLIO
                                       │
            ┌──────────────────────────┴──────────────────────────┐
            ▼ (40% - 50%)                                         ▼ (50% - 60%)
  PRIVATE DEBT ASSETS (CREDIT)                         REAL ESTATE SYNDICATIONS (EQUITY)
┌───────────────────────────────────────┐             ┌───────────────────────────────────────┐
│ • Focus: Monthly Cash Flow            │             │ • Focus: Wealth Growth & Tax Havens   │
│ • Assets: 1st-Lien Bridge Loan Funds  │             │ • Assets: Class B Multifamily, Ind.   │
│ • Yield: 9.0% – 11.0% Net Cash Flow   │             │ • Target: 15% – 18% Net IRR Target    │
│ • Account: SDIRA / Solo 401(k) / Ret. │             │ • Account: Personal Taxable / Trusts  │
│ • Role: Replaces fixed income drag    │             │ • Role: Depreciation shelters income  │
└───────────────────────────────────────┘             └───────────────────────────────────────┘
The Allocation Framework
- Private Debt as the Cash-Flow Foundation: Allocate capital to private debt funds to generate reliable, high-yield cash flow that replaces traditional fixed-income allocations. Deploy these investments through tax-advantaged accounts (such as a Solo 401(k) or Self-Directed IRA) to shield ordinary interest income from top-bracket taxes.
- Equity Syndications as the Growth and Tax Shield: Deploy taxable capital into real estate syndications focused on value-add multifamily, industrial logistics, or build-to-rent developments. The passive depreciation losses from cost segregation studies shield the quarterly cash flow from current taxes, while the long-term equity appreciation compounds wealth over a three-to-seven-year period.
- Dynamic Rebalancing: Use the monthly cash yields generated by private debt funds to fund capital calls for new equity syndications, creating a self-sustaining private investment engine.
Strategic Action Checklist for Accredited Investors
- Confirm Accreditation Credentials: Secure an accreditation verification letter from your CPA, attorney, or an approved verification service to facilitate access to Rule 506(c) offerings.
- Define Your Primary Investment Objective: Determine whether your current financial priority is generating high, predictable monthly cash flow (Private Debt) or building tax-sheltered, long-term equity appreciation (Equity Syndications).
- Choose the Optimal Account Structure:
- Hold Private Debt Funds within tax-advantaged retirement wrappers (Solo 401(k), Checkbook SDIRA) to prevent high ordinary income tax drag.
- Hold Equity Syndications within taxable personal accounts or family trusts to fully capture pass-through depreciation write-offs and long-term capital gains treatments.
- Audit the Sponsor’s Underwriting Assumptions: Scrutinize exit cap rates, verify that interest rate caps are in place for floating debt, check historical default rates, and ensure the sponsor has material financial commitments (skin in the game) alongside outside investors.
- Examine Waterfall Distribution Terms: Check that equity offerings include a cumulative preferred return (6% to 8%+), look for clear clawback protections, and review the GP promote hurdle structure.
- Verify Collateral Margins: For private debt allocations, confirm the fund maintains a conservative average weighted LTV below 65% to 70%, with primary capital secured by first-lien deeds of trust.
- Review the Legal Documentation Package: Read the complete Private Placement Memorandum (PPM), Operating Agreement, and Subscription Agreement with an independent securities attorney before wiring capital.